Proposition [efr-001D]
Proposition [efr-001D]
The set of indexed stochastic charts is just the set of commutative squares in \mathsf {Kl}(\Delta ) of this form:
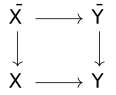
where this exponential denotes the iterated Cartesian product in convex spaces. An element of this set clearly gives a commutative square, because for each y \in Y, there is a square which deterministically chooses that y, and uses the given family of distributions on \bar {Y}_y depending on \bar {X}. This mapping is injective, since each map \bar {X} \to \Delta (\bar {Y}_y) can be recovered as a conditional distribution, and the convex combination of ys is merely the underlying distribution on Y. On the other hand, by choosing conditional distributions, it is also seen to be surjective, finishing the proof.